
WS EkinsGuinness Dynamic Growth Fund
Overview
Summary
- Dynamic asset allocation between equities, bonds, commodities and cash
- Aim is to capture equity market upside in bull markets but to reduce drawdowns (peak to trough falls) in bear markets
- All exposure achieved through Exchange Traded Funds which have low costs and low dealing charges
- Avoids style bias – both asset allocation and equity focus change according to market conditions
- Suitable as a potential diversifier within a broader portfolio due to generally low correlation and lower volatility than Equities
- Can also be a core holding for investors who prefer not to make asset allocation changes themselves
Investment Approach
The two most important drivers for investment decisions are fundamental value and market trends. Fundamental value determines the potential over the medium/long term but can be a poor indicator of price movements in the short term. Market trends (including momentum and overbought signals) can be a good leading indicator of future price movements but can be dangerous if fundamental value is ignored. Neither analytic should be used in isolation but it is logical to select investments based objectively according to a combination of fundamental value and market trends which are independent of opinion, forecasts and emotion.
Performance
(as at 30 September 2026)
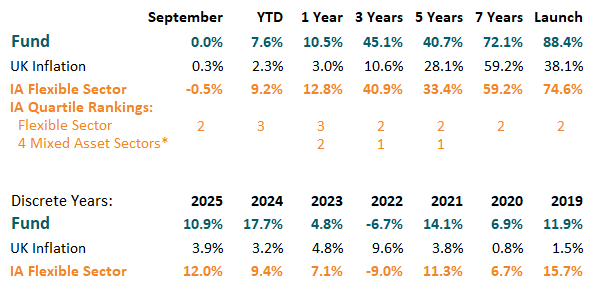
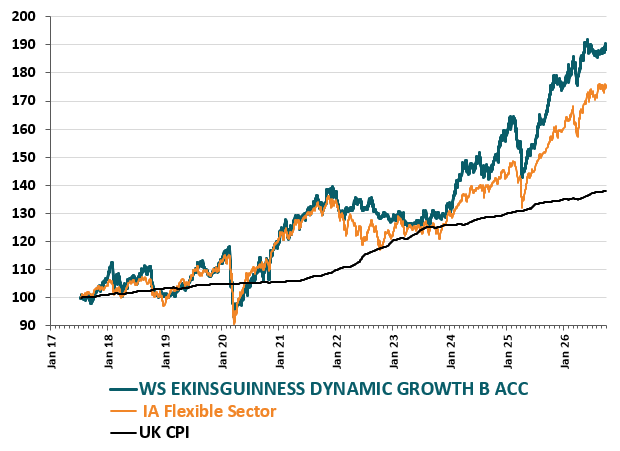
Performance shown is the total return (net of fees & costs) for the Accumulation B share class. Inception date was 12 July 2017. The Fund is not managed against any benchmark. The Investment Association Flexible Sector and UK Consumer Price Inflation are shown as Comparator benchmarks as per FCA PS 19-04. The IA Flexible Sector contains a wide array of funds with a flexible mandate, hence the comparator, but many of them have different investment objectives and profiles. Past performance is not a reliable indicator of future performance. Source: Ekins Guinness LLP.
Key Facts
Structure & Administration
| Structure |
UCITS / ISA |
Authorised Corporate Director |
Depositary | Custodian | Auditor |
Income / Accumulation |
Dividend Payment Dates |
Valuation & Cut Off |
Comparator Benchmark |
|---|---|---|---|---|---|---|---|---|---|
|
UK Authorised OEIC |
Yes |
Waystone Management (UK) Limited |
BNY Mellon |
BNY Mellon |
KPMG |
Both |
31 January & 31 July |
12 noon daily |
MSCI World Index |
Share Classes
| Share Class |
Minimum Holding |
Managment & Administration Fee |
Ongoing Charges Figure |
ISIN | SEDOL |
|---|---|---|---|---|---|
|
Z Accumulation GBP |
£200,000 |
0.45% |
0.60% |
GB00BLFFGD12 |
BLFFGD1 |
|
Z Income GBP |
£200,000 |
0.45% |
0.60% |
GB00BLFFGC05 |
BLFFGC0 |
|
B Accumulation GBP |
£5,000 |
0.70% |
0.85% |
GB00BD8YW428 |
BD8YW42 |
|
B Income GBP |
£5,000 |
0.70% |
0.85% |
GB00BD8YW758 |
BD8YW75 |
Managers

Charles Ekins
Charles is the founder and Chief Executive of Ekins Guinness LLP. Previously he was Chief Investment Officer at Valu-Trac Investment Management, prior to which he spent 19 years at Morgan Grenfell (Deutsche) Asset Management where he was a portfolio manager, member of the Investment Policy Committee and client director. He read Maths with Computing Science at Bristol University and has an MBA from the City University Business School. Charles is a Director of the Herald Worldwide Technology Fund (Dublin OEIC).

Jasper Falk
Jasper has over 20 years experience in Investment Banking. He established and managed JPMorgan’s Global Inflation trading business which assisted Pension Funds and Asset Manager clients in hedging and managing their liabilities. He was also a member of the Fixed Income Management Committee. Jasper read Engineering and Management Studies at St Catharine’s College Cambridge, and holds the Financial Times Non-Executive Director Diploma.
Holdings
(as at 31 September 2026)
Portfolio Holdings
Equity Analysis
Investment Commentary
as at 30 September 2026
The Fund was flat in September against a backdrop of a small price fall in world equity markets (although this translates into a small rise in GBP terms due to Sterling weakness). Gilts, US Treasuries and Gold all gave negative returns, while Oil was up 16%.
Since launch on 12th July 2017 the Fund has returned 88.4% which compares with a return of 74.6% from the Investment Association (IA) Flexible Sector. Against all 680 funds in the four IA Mixed Asset Sectors (Flexible Sector plus the 0-35% Shares, 0-60% Shares & 40-85% Shares Sectors), the Fund is ranked in the second quartile over 1 year and in the first quartile over 3 and 5 years. Against the IA Flexible Sector, the Fund is in the second quartile since inception.
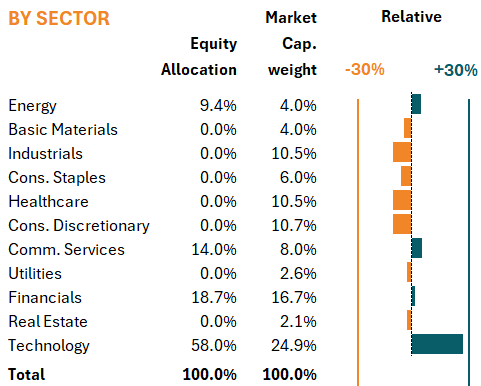
In September, the strongest performing global sectors in September were Technology (+6.6% in GBP terms) and Communication Services (+5.7%). The concentration in Technology and Communication Services is borne out by the fact that 8 out of the 11 global sectors gave a negative return in September, with the weakest sector being Materials (-5.4%).
The S&P 500 and world equity markets in general ended September close to their all time highs, driven by continued high expectations for future corporate earnings over the next 12 months. At the moment, this is all markets seem to care about, maybe with good reason, and the worries causing weak bond markets are hitherto being ignored.
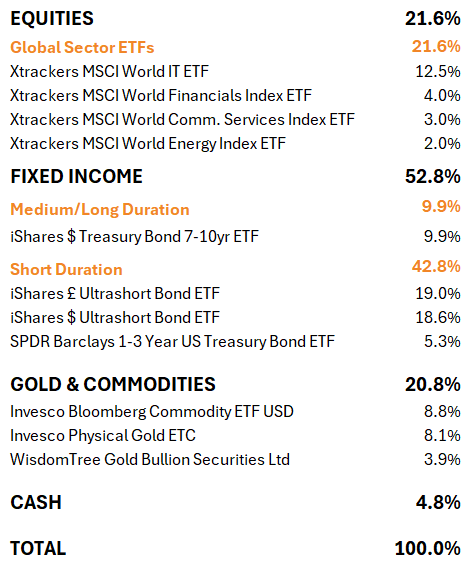
The Fund is currently in pretty much full capital preservation mode. The Equity allocation is only 22%. We have a new token 10% exposure to US 10 Yr Treasuries because they became oversold. Gold is 12% and a diversified basket of Commodities is 9% of the Fund. Otherwise we are holding 43% in very short duration Governments bonds while we wait to see what happens.
It may be worth pausing to comment on our asset allocation approach. We are quite happy to be fully invested in equity markets, and that is our preferred position, but only if Equity valuation is reasonable and momentum is supportive. When Equity valuation and/or momentum give warning signals, our model can and does move to a very defensive position, and can even be zero in Equities in extremis. There have been quite a few examples over the life of the Fund since 2017 when the Fund has become very defensive (2018, Covid 2020, much of 2022 etc), similar to the current low allocation in Equities. In the event, those Equity markets falls all turned out to be only “medium” setbacks which were also fairly short-lived. We mention this because, if any of these had turned out to be major bear markets, we think the Fund would have been well-positioned “just in case”. The worst two equity bear markets this century were the 2008 Global Financial Crisis (peak-to-trough price fall of 55%) and 2000-2003 Tech crash (44%). This Fund (launched in 2017) hasn’t been tested in such conditions but we can say that the model we use was, on a simulated basis, very defensive through both two terrible periods.
Our message continues to be that we are still sitting on the sidelines. Continued high expectations of future earnings growth is a major positive, but the starting point for equities is that they are expensive – although obviously not quite so expensive assuming that earnings growth does comes through.
The more subtle point is that much depends on what valuation measurements one looks at. The bulls point out that the forward Price/Earnings Ratio (ie assuming strong earnings growth does materialise) is high but not extreme and therefore sustainable. Our concern is that the PE Ratio depends on reported earnings which includes uncertainties over depreciation. In a world when the earnings growth is coming from massive AI capex, it is hard to know how reliable reported earnings are because of depreciation uncertainty. We prefer to look at cash earnings, which gives a much more worrying valuation picture. This ultimately explains our caution over Equity markets, as shown below.
Documents
Links to external sites
Umbrella Documents
Reports
How to Invest
via Platforms
Directly
The WS EkinsGuinness Dynamic Growth Fund is available on the following platforms:
| Allfunds | Aegon | AJ Bell | Ascentric |
|---|---|---|---|
|
Aviva |
Barclays |
FNZ |
Hargreaves Lansdown |
|
Interactive Investor |
Novia |
Nucleus |
Pershing |
|
Quilter |
Transact |
Zurich |
|
Contact Ekins Guinness LLP
- Call 01264 738989